1. Building code
When your home was permitted. In Miami-Dade, homes permitted after September 1, 1994 under the South Florida Building Code can qualify, and so can homes under the 2001 Florida Building Code.
Your home's hurricane features can lower the wind part of your insurance, but only if they're on the state form. I find every feature your house has, photograph it, and put it on the current form so your insurer has what it needs.
Every wind mitigation inspection done on or after April 1, 2026 has to be on the new OIR-B1-1802 (Rev. 04/26) form. It has nine questions now instead of seven. It adds your home's wind region and the slope of your roof, and a FORTIFIED roof certificate can count as proof for several answers.
If yours was done in the five years before that date and nothing on the house changed, Citizens says it still takes the old version. Other insurers make their own call, so check with your agent before you pay for a new one.
Each question is a chance at a credit, so here's what I look for:
When your home was permitted. In Miami-Dade, homes permitted after September 1, 1994 under the South Florida Building Code can qualify, and so can homes under the 2001 Florida Building Code.
New for 2026. All of Miami-Dade sits in the High-Velocity Hurricane Zone, the strictest wind zone in Florida.
New for 2026. I measure the section that covers most of the house, 6 in 12 or steeper, or under that.
I check the roof type and look up its permit and product approval. A permitted roof that meets the current code does best.
Up in the attic I measure the nail size and spacing that hold the roof sheathing down.
Toe nails, clips, single wraps or double wraps. This is what keeps your roof on, and wraps score best.
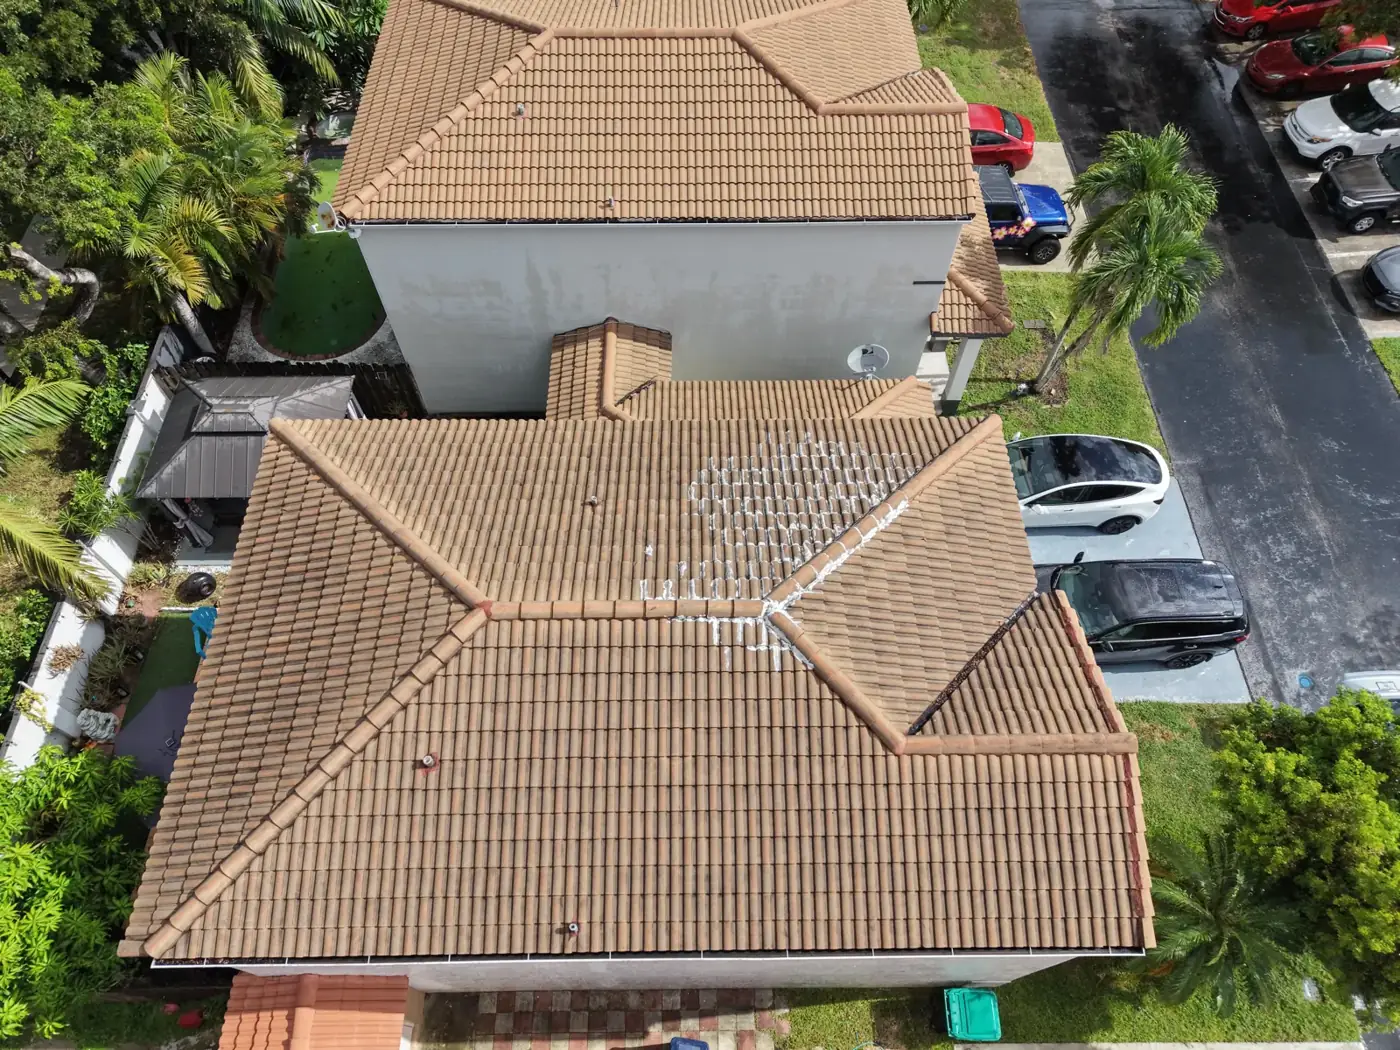
A hip roof, sloped on all four sides, handles wind better than a gable roof. I measure it so the form gets it right.
A sealed layer under the roof covering. Regular felt doesn't count, and it's usually only provable from the reroof permit or receipt.
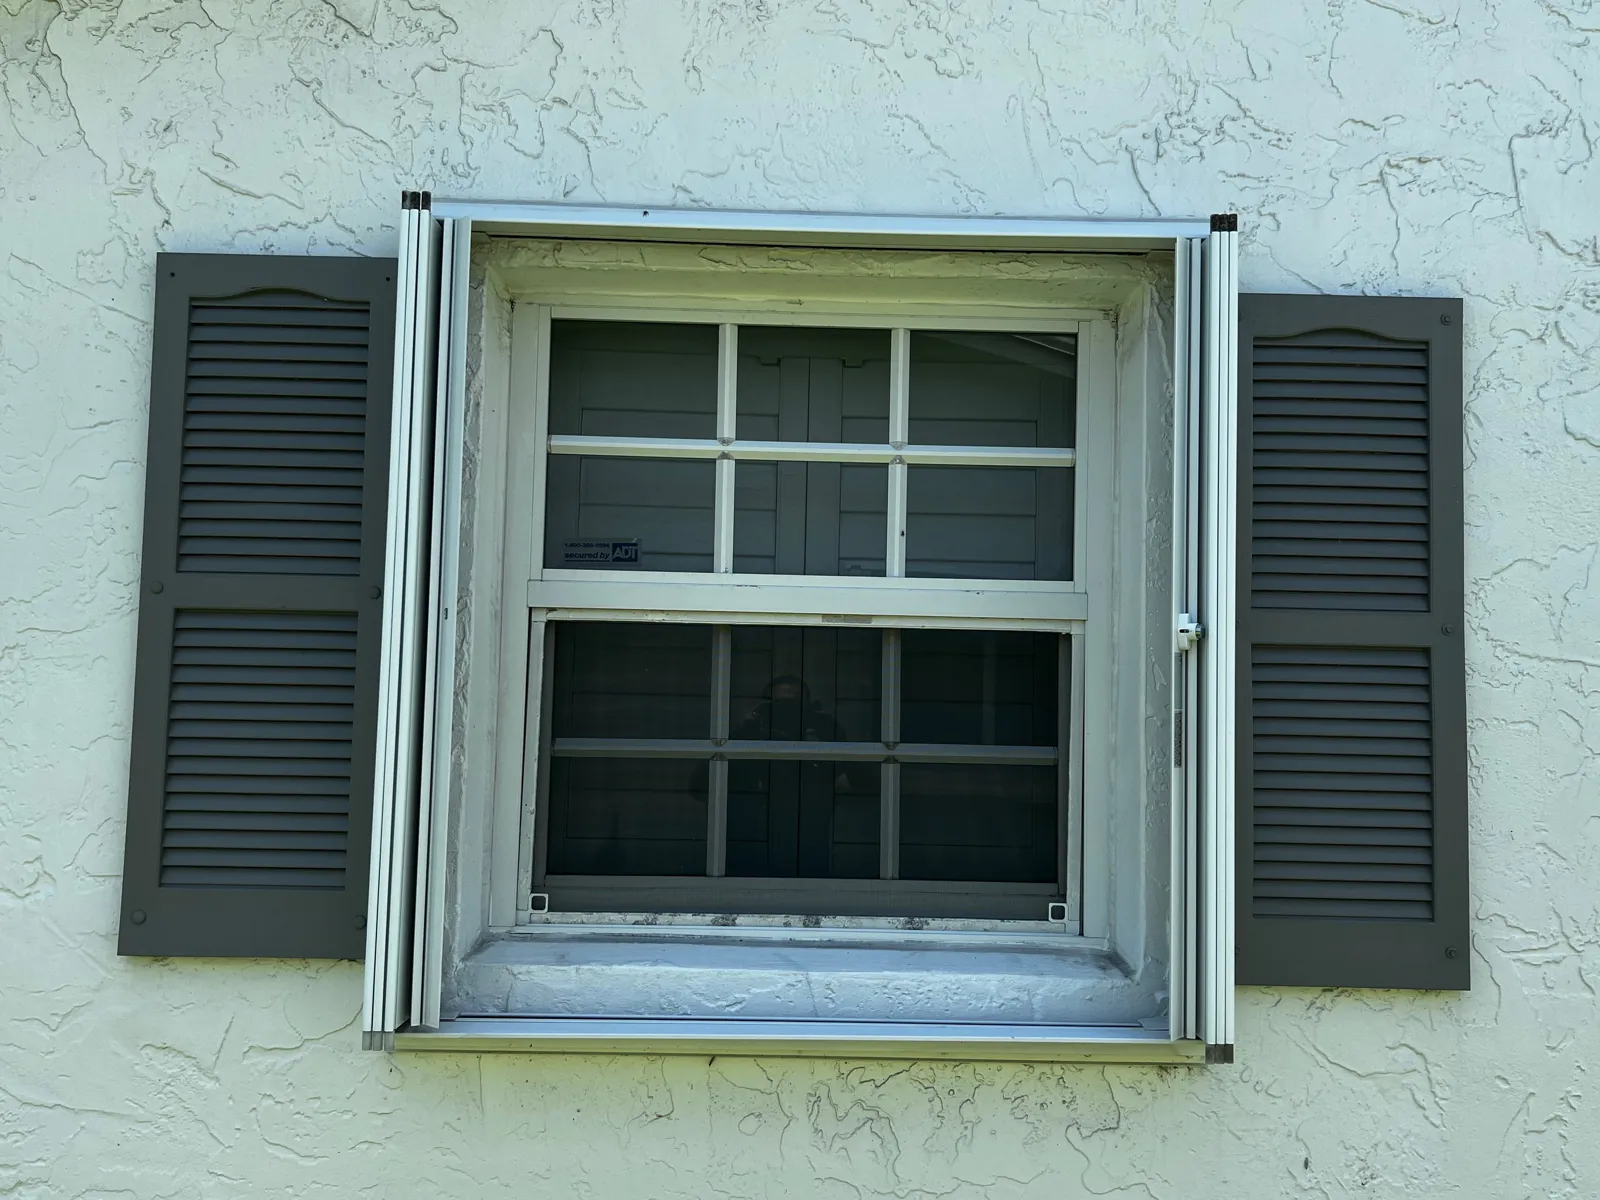
Every window, door, skylight and the garage door. One unrated garage door can cost you the whole credit, so I photograph the approval labels.
Florida insurers have to offer discounts for hurricane features. The catch is that they can only give you credit for what's on the form, so a feature nobody wrote down doesn't save you anything.
Most homes I inspect have at least one feature the owner didn't know counted. I can't promise you a dollar amount, since that's up to your insurer. What I can promise is that every feature your house really has ends up on the form with a photo behind it.
Want to know what you'd pay first? Here's the wind mitigation cost page.
Need a 4 point too? I do both in one visit, so have a look at 4 point inspections in Miami.
I'm a U.S. military veteran and a Florida licensed home inspector (HI18810), and this is my family's business with my wife Lumey and our son Jason. When you call, you get me, and when the inspection happens it's me on your roof and in your attic, with no subcontractor.
I don't work for the insurance company. I work for you, and I'll tell you the truth about the house in English o en español. You can read my 8 Google reviews (5.0 stars), check my InterNACHI profile, or see everything I do on my main website.
Up to 5 years, as long as nothing material on the house has changed and nothing on the form turns out to be wrong. A new roof, new windows or a new garage door is a good reason to get a new one.
Every inspection done on or after April 1, 2026 has to be on the new form. Citizens says it still accepts the old version if it was done within the five years before April 1, 2026. Other insurers set their own rules, so ask yours.
I won't promise a number, because it depends on your insurer and your house. Florida insurers have to offer discounts for hurricane features, but they can only credit what's on the form.
The My Safe Florida Home program offers free inspections for owner-occupied, homesteaded single-family homes when it has funding. If you qualify and you're not in a hurry, apply. If your insurer gave you a deadline, call me.
Yes. Insurers have to accept the form from a licensed home inspector who has finished the required hurricane mitigation training. The person who signs has to do the inspection personally.
Yes. Citizens says it can order its own independent inspection to verify a form. That's one more reason every answer on mine has a photo behind it.
Most insurance reports go out the same day, and the rest go out by the next morning.